A Damaged Roof Is a Replacement — Not a Patch Job
Storms lift, crease, tear and strip shingles. Insurers offer a handful of replacement tabs or call it "cosmetic." We prove the real scope — so your roof is actually made whole.
Roof Damage Claims in Ohio
After a storm, the insurance company's adjuster spends a few minutes on the roof and offers to replace a handful of shingles — or writes the damage off as "cosmetic" or "wear and tear." But a roof with missing, lifted and creased shingles is a compromised system: it lets water in, and it keeps failing until it's properly restored.
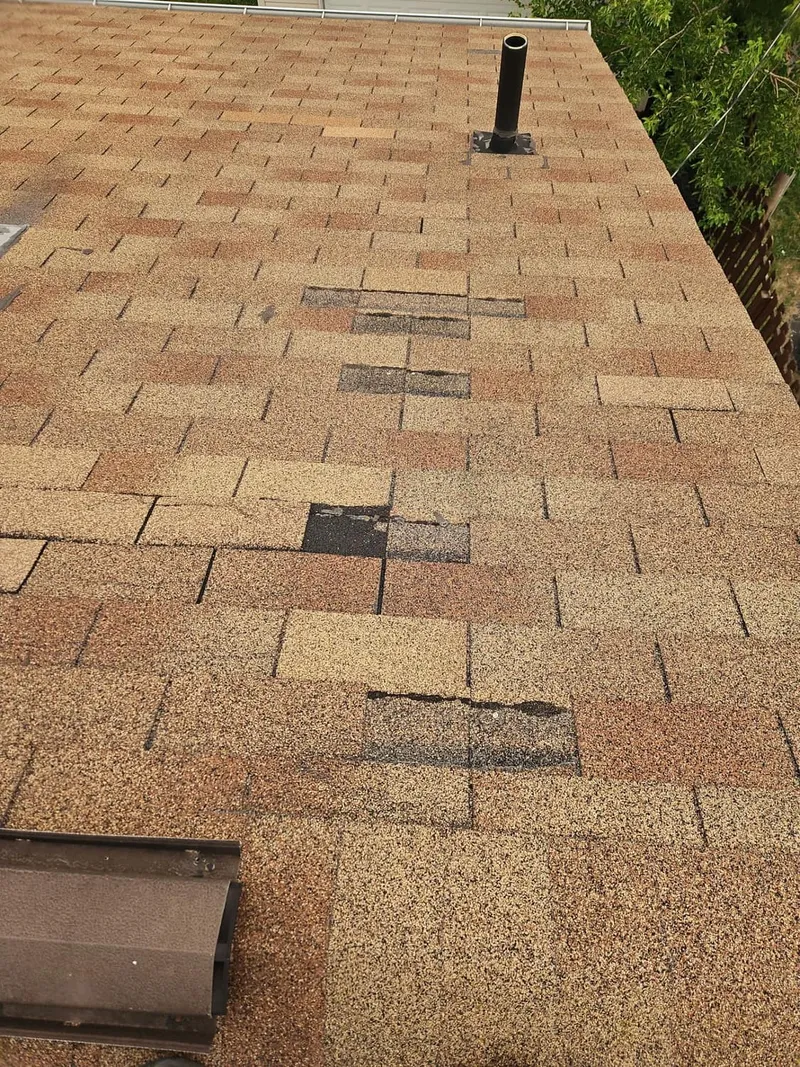
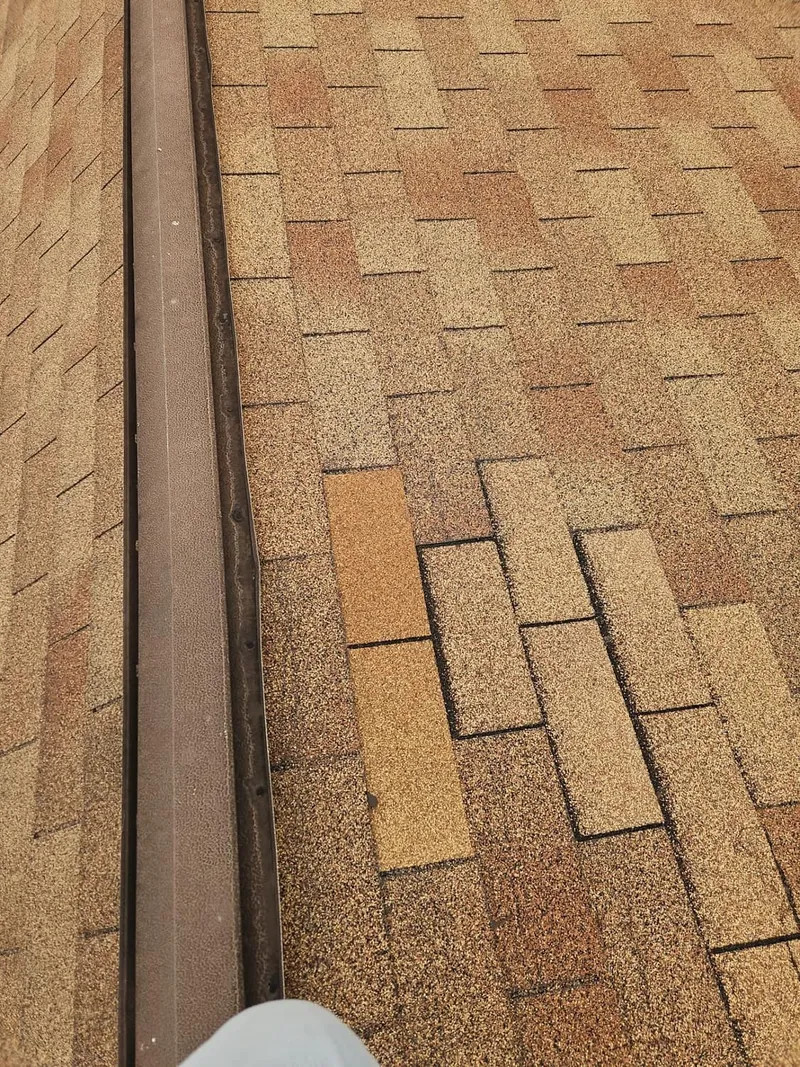
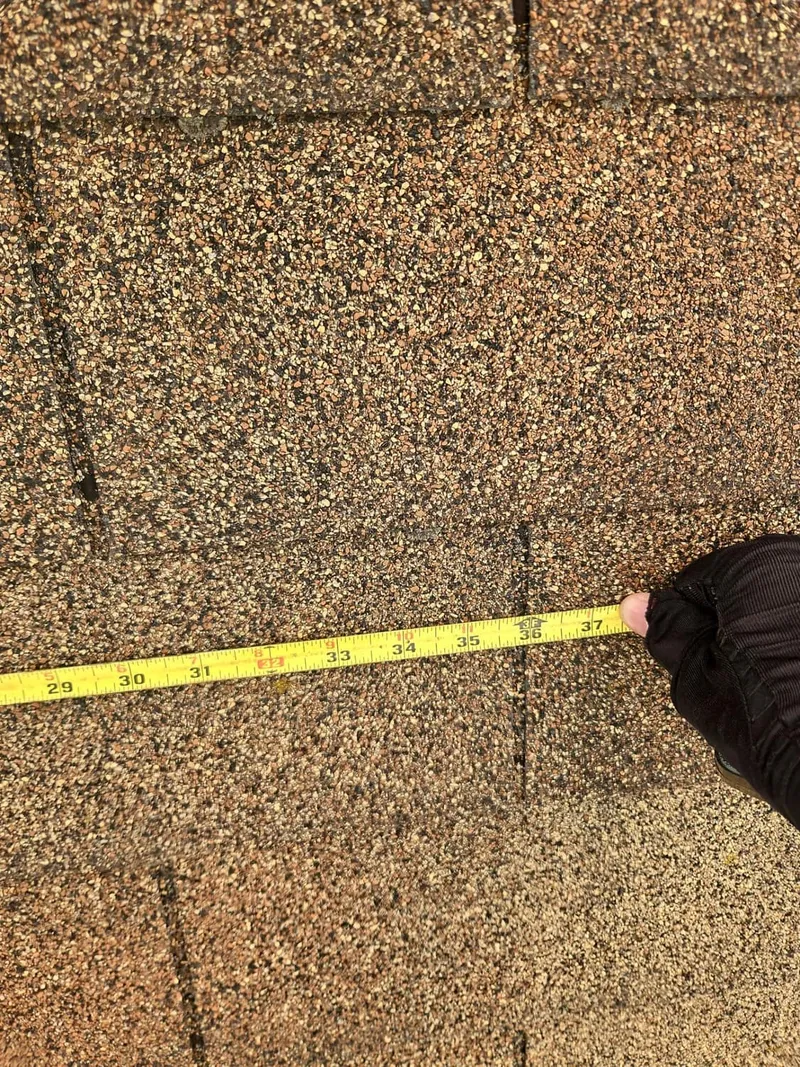
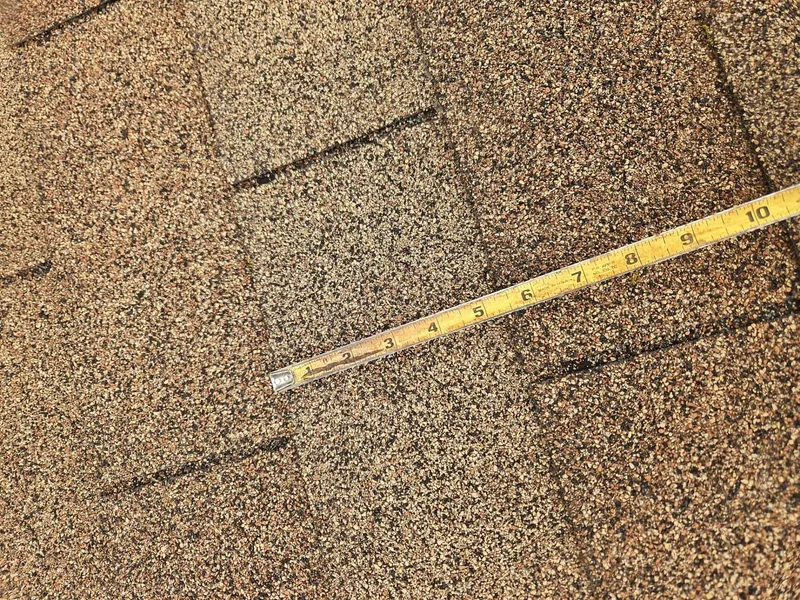
We inspect the way it should be done — documenting the damage on every slope, not just the one from the driveway; measuring and marking each area; and checking the exposed decking, flashing, drip edge and gutters. When the pattern spans multiple roof planes, that's a storm loss — and often a full replacement, not a patch.
As public adjusters we work for you, not the insurer. Our founder began his career as a general contractor, so we read the roof the way a builder does. We handle roof claims across Ohio and our Florida, Texas and Louisiana office markets. Hurricane winds can cause roof damage that isn't always immediately visible. Learn more about Florida hurricane damage insurance claims.
Documented Claim
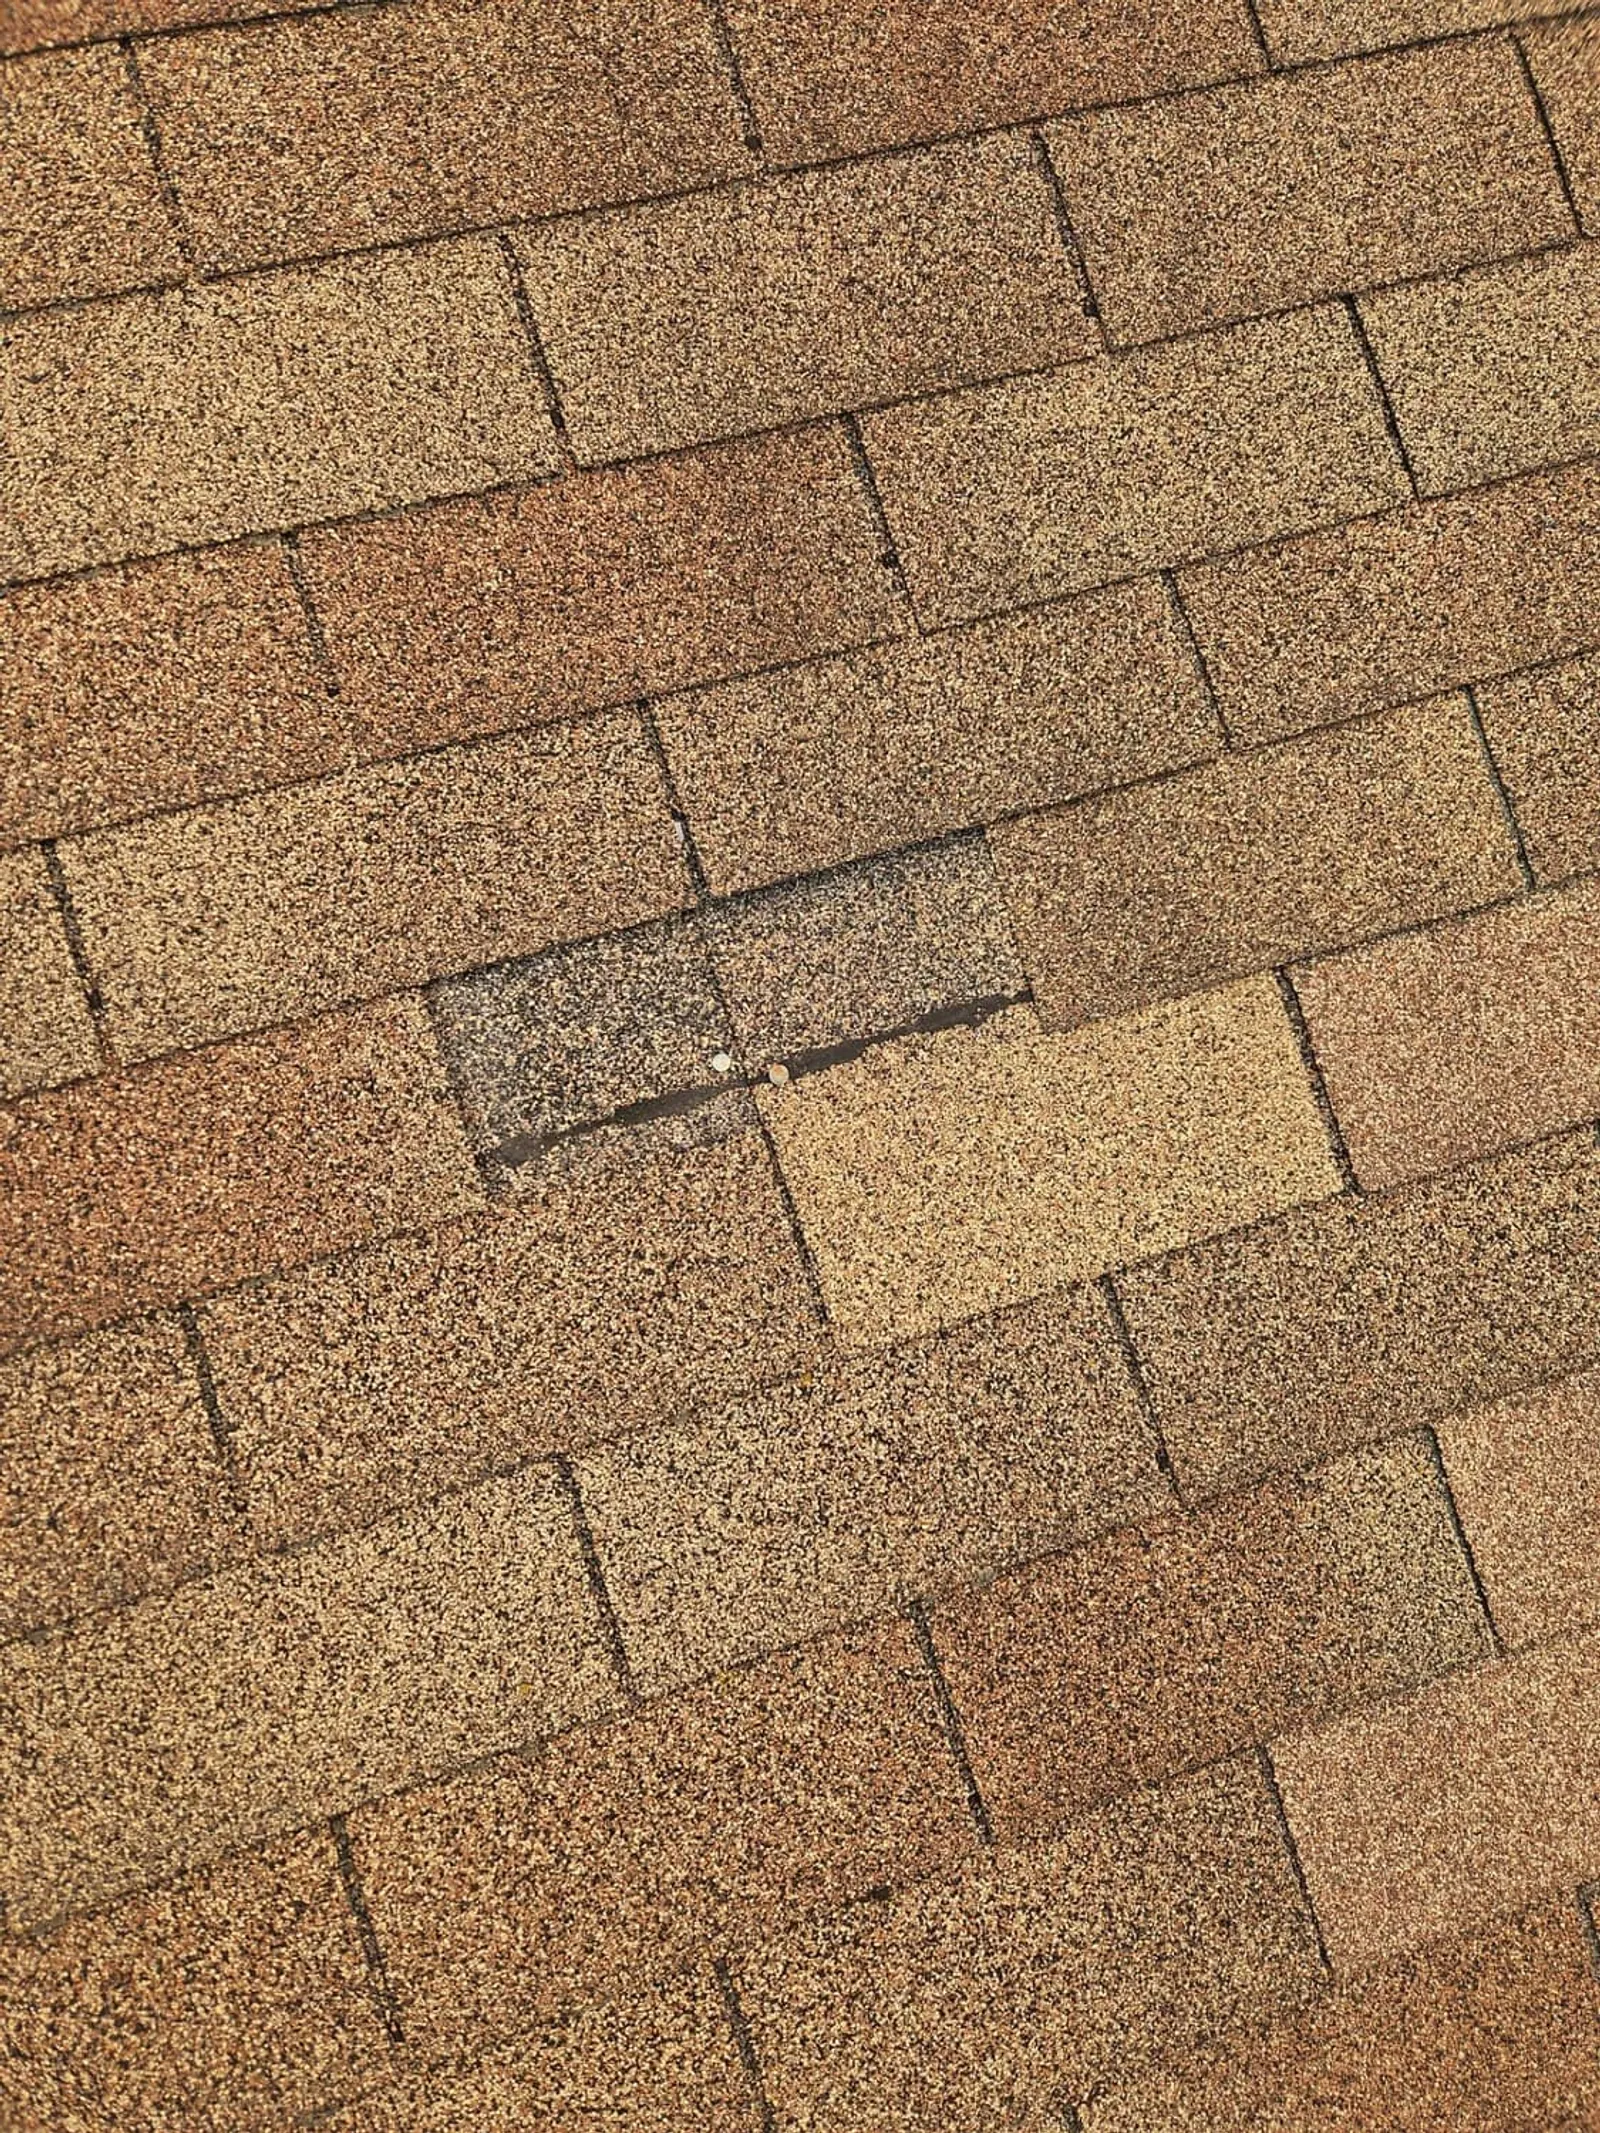
Inside a Roof Loss — Euclid, OH
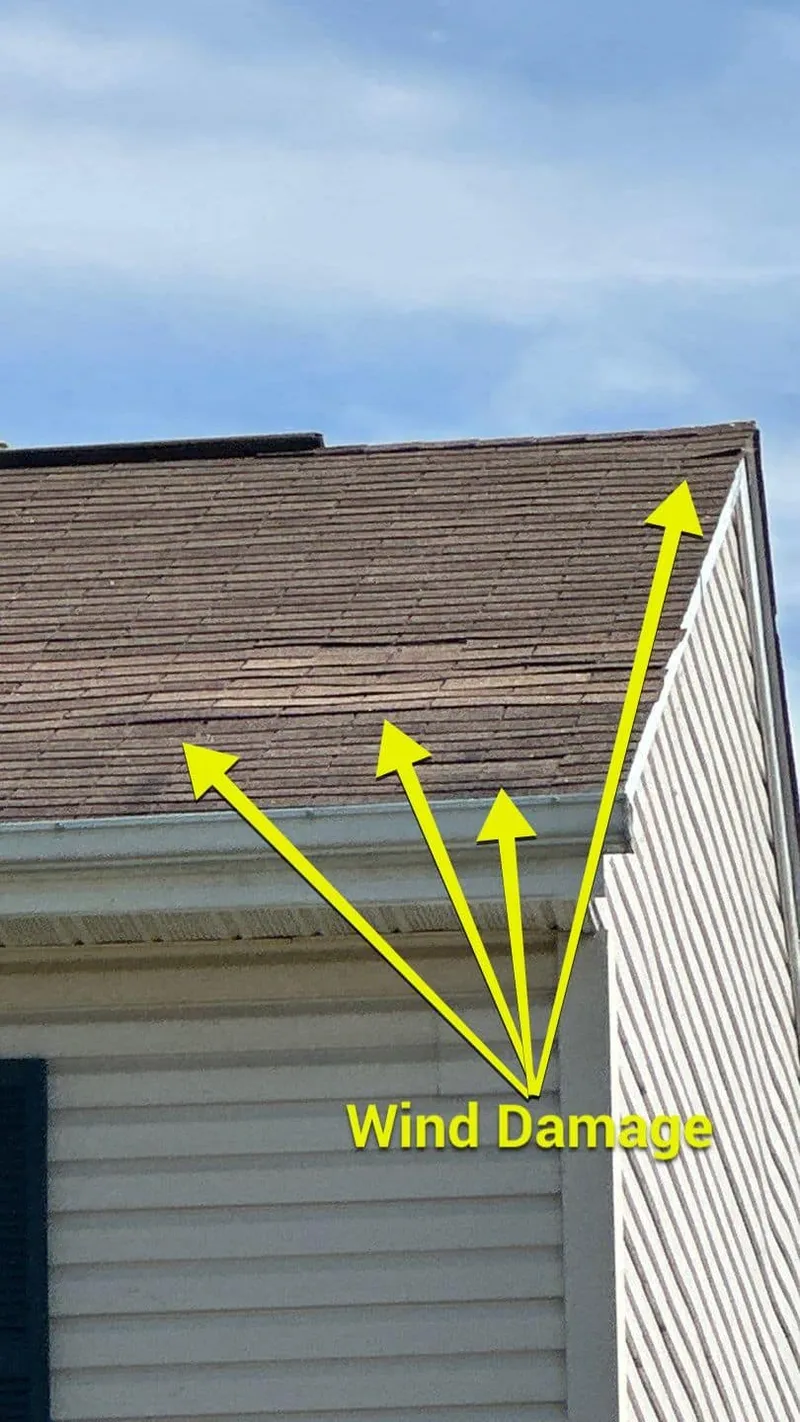
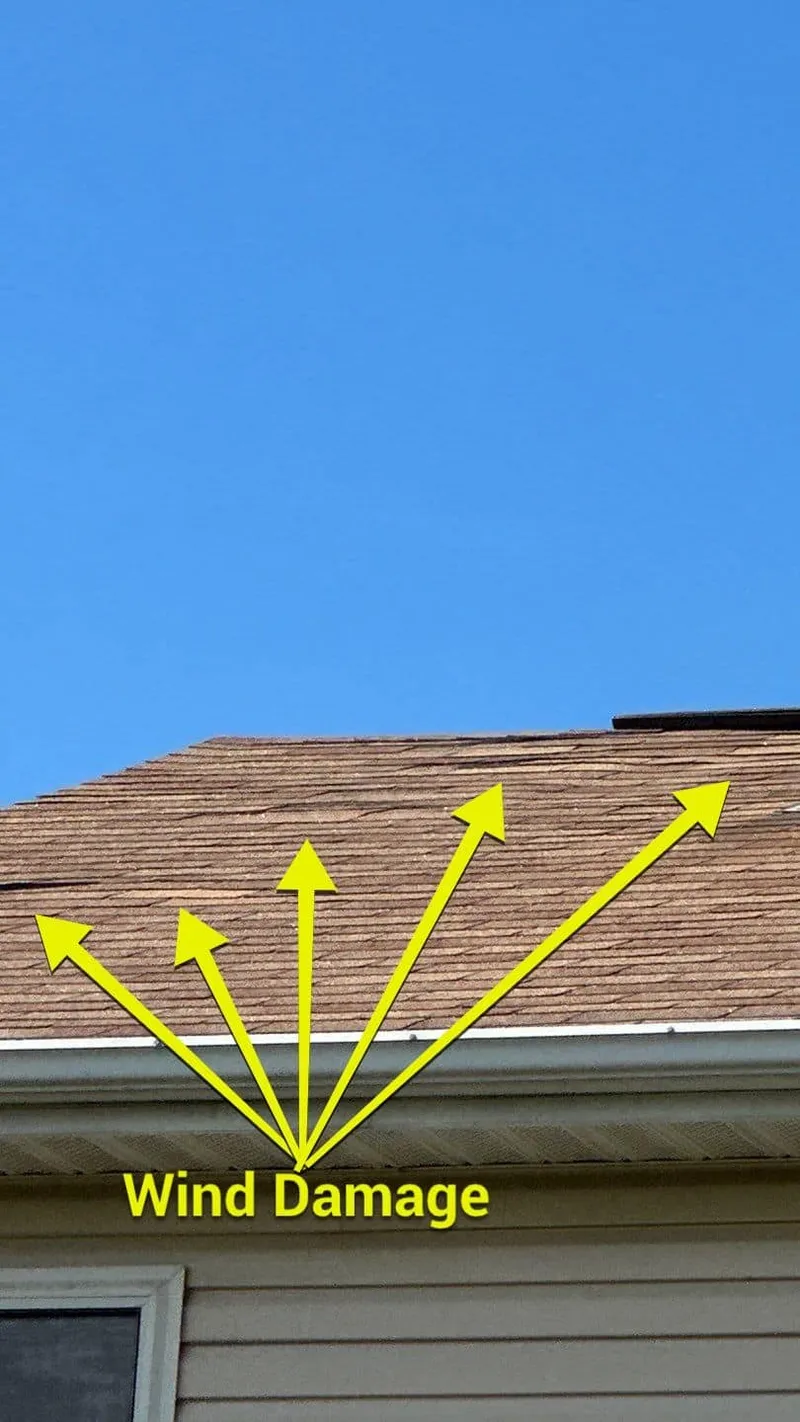
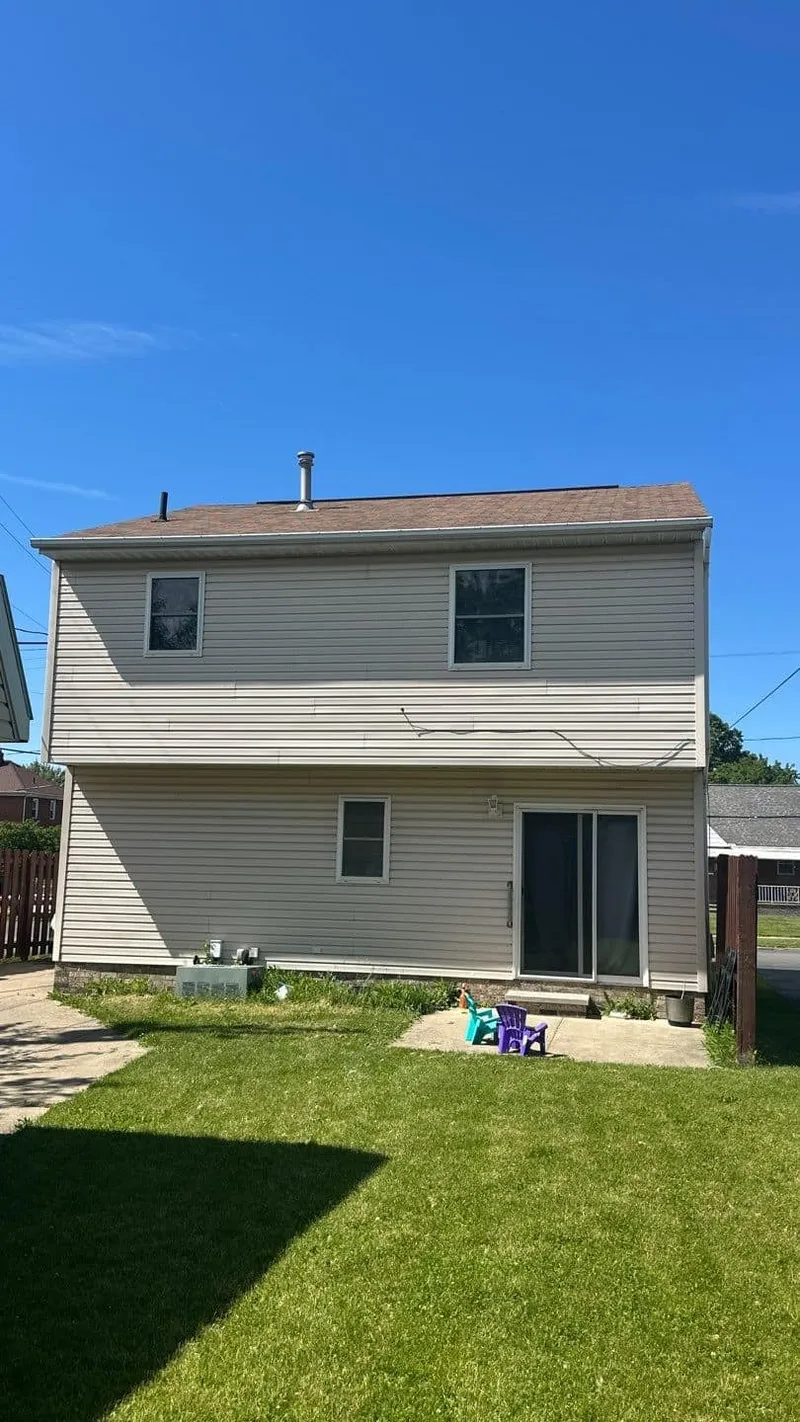
Photos from one of our Ohio roof claims in Euclid (Greater Cleveland) — wind-damaged shingles documented slope by slope. This is the level of documentation we bring to every loss — the evidence that turns a "few shingles" offer into a fair settlement. (Client details withheld for privacy.)
Documented Claim
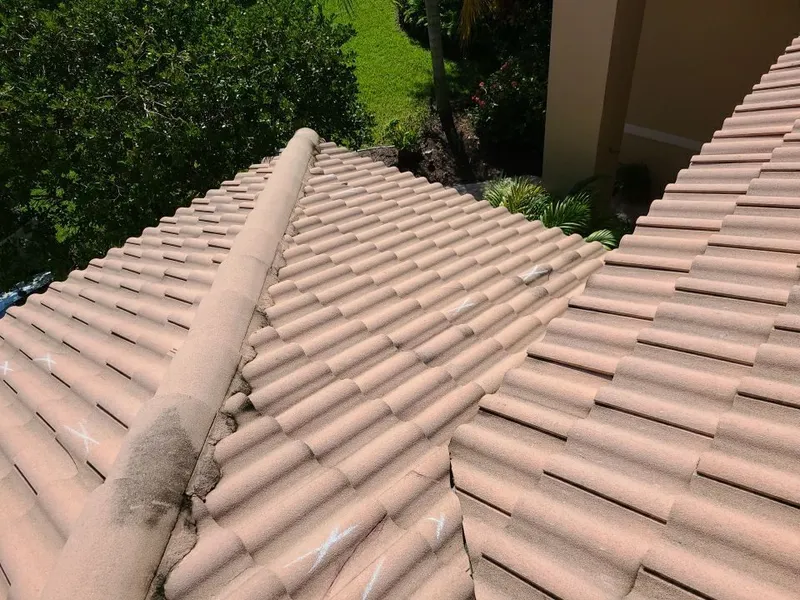
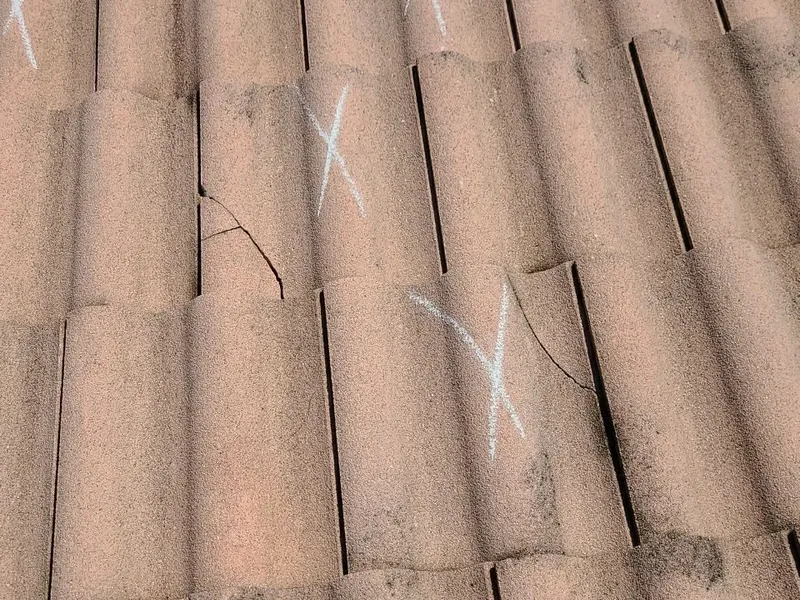
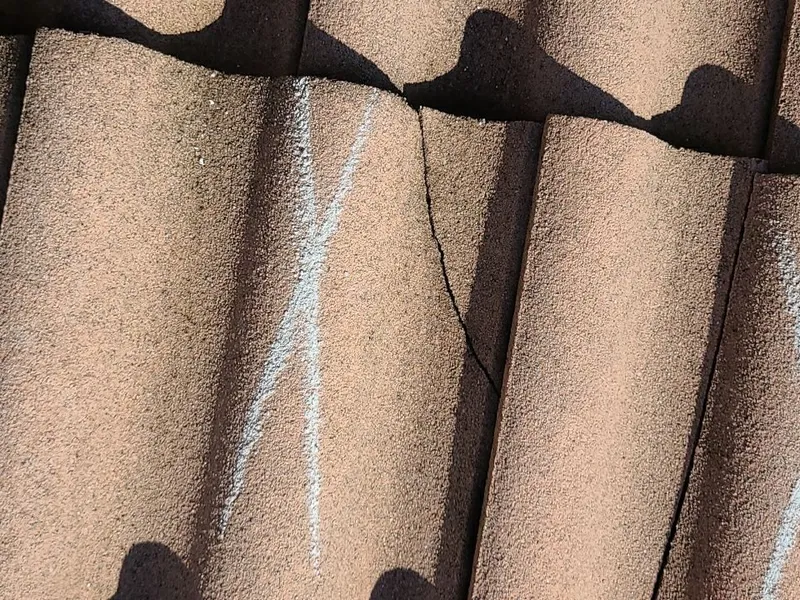
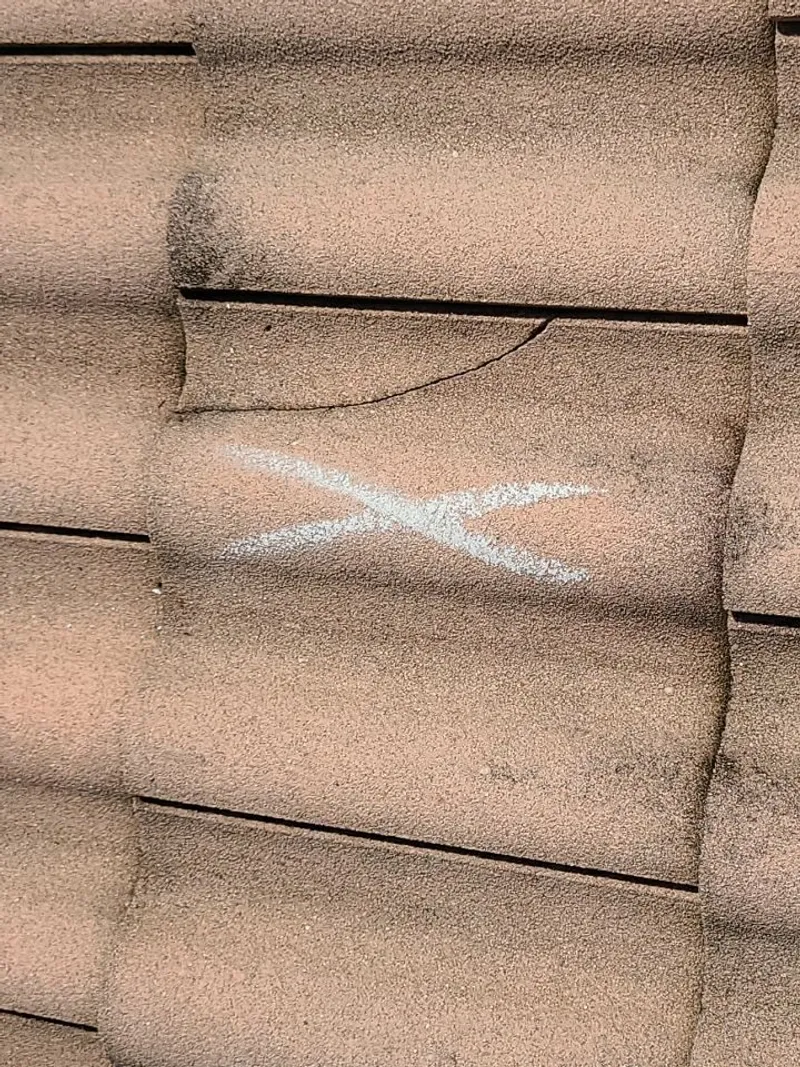
Inside a Roof Loss — Fort Lauderdale, FL
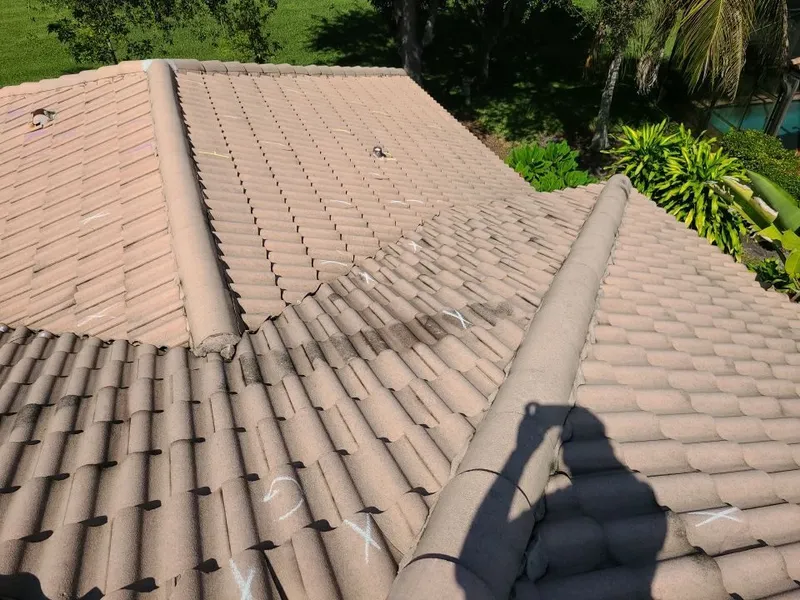
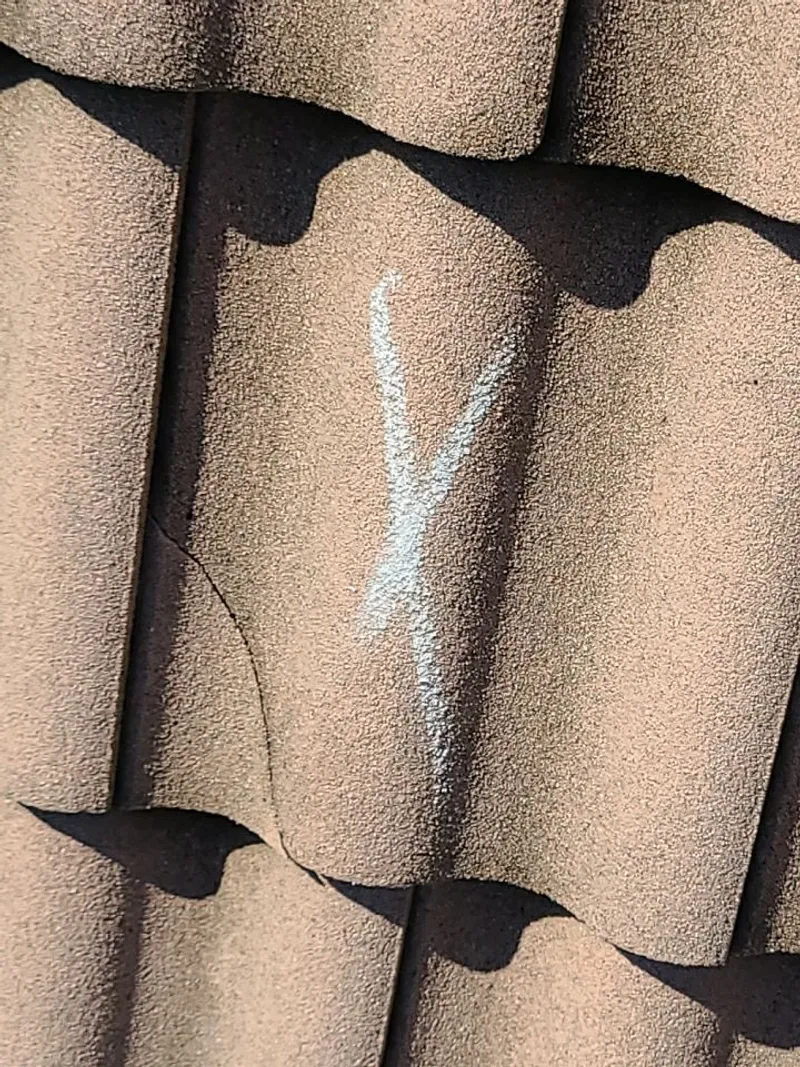
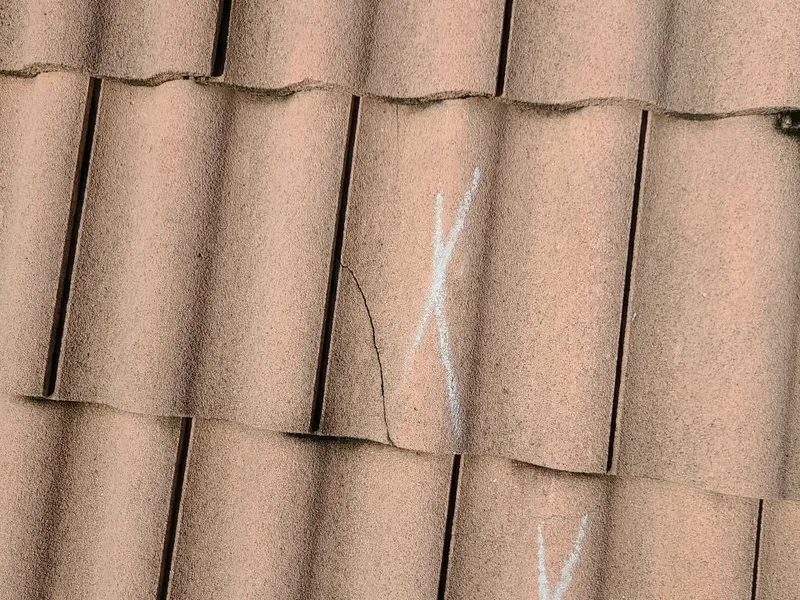
A Florida concrete barrel-tile roof after a storm — dozens of cracked and fractured tiles, each chalk-marked and photographed slope by slope. On tile roofs a handful of "broken tiles" is often the visible edge of a system-wide loss, and discontinued tile forces a full replacement to match. This is the documentation that turns a spot-repair offer into a fair settlement. (Client details withheld for privacy.)
What Roof Claims Often Leave Out
- Missing, lifted, creased or torn shingles written off as “old”
- Damage across multiple slopes — not just the one the adjuster saw
- Exposed decking and underlayment
- Flashing, drip edge, vents and gutters
- Matching — when discontinued shingles force a full replacement
- Code-required upgrades triggered by a re-roof
- Interior leaks and water damage that follow a failing roof
Other Damage We Handle
Related Services
Roof Damage After a Storm?
We'll document the full scope and deal with the insurer for you. Our fees are contingency-based and subject to applicable state law and the terms of your written agreement.