Fire Claim Denied, Delayed, or Underpaid?
You've already filed — and the denial or the offer doesn't feel right. A licensed public adjuster can step in after you've filed to reopen, re-document, and fight for the settlement your fire loss is actually owed.
Already filed, and the outcome feels wrong?
After a fire, the insurance company assigns an adjuster whose job is to keep the payout low. If your claim came back denied, delayed, or with an offer that won't come close to making you whole, that's not necessarily the final word.
As public adjusters, we work for you — not the insurer. We can take over an existing fire claim at any stage: after the carrier's inspection, after an offer, or after a denial. We re-document the full loss and dispute or supplement the claim on your behalf.
Our founder began his career as a general contractor, so we read a fire loss the way a builder does — capturing the smoke contamination, weakened framing, water and mold, ductwork, and code-required repairs the carrier's estimate so often leaves out.
Where You Stand
Denied, underpaid, or delayed — we can help with all three
Your fire claim was denied
A denial isn't always the end. Claims get denied over disputed cause, alleged policy exclusions, missed deadlines, or paperwork the insurer says is incomplete. We review the denial letter and your policy, rebuild the documentation, and challenge the basis for the denial.
The offer doesn't cover the loss
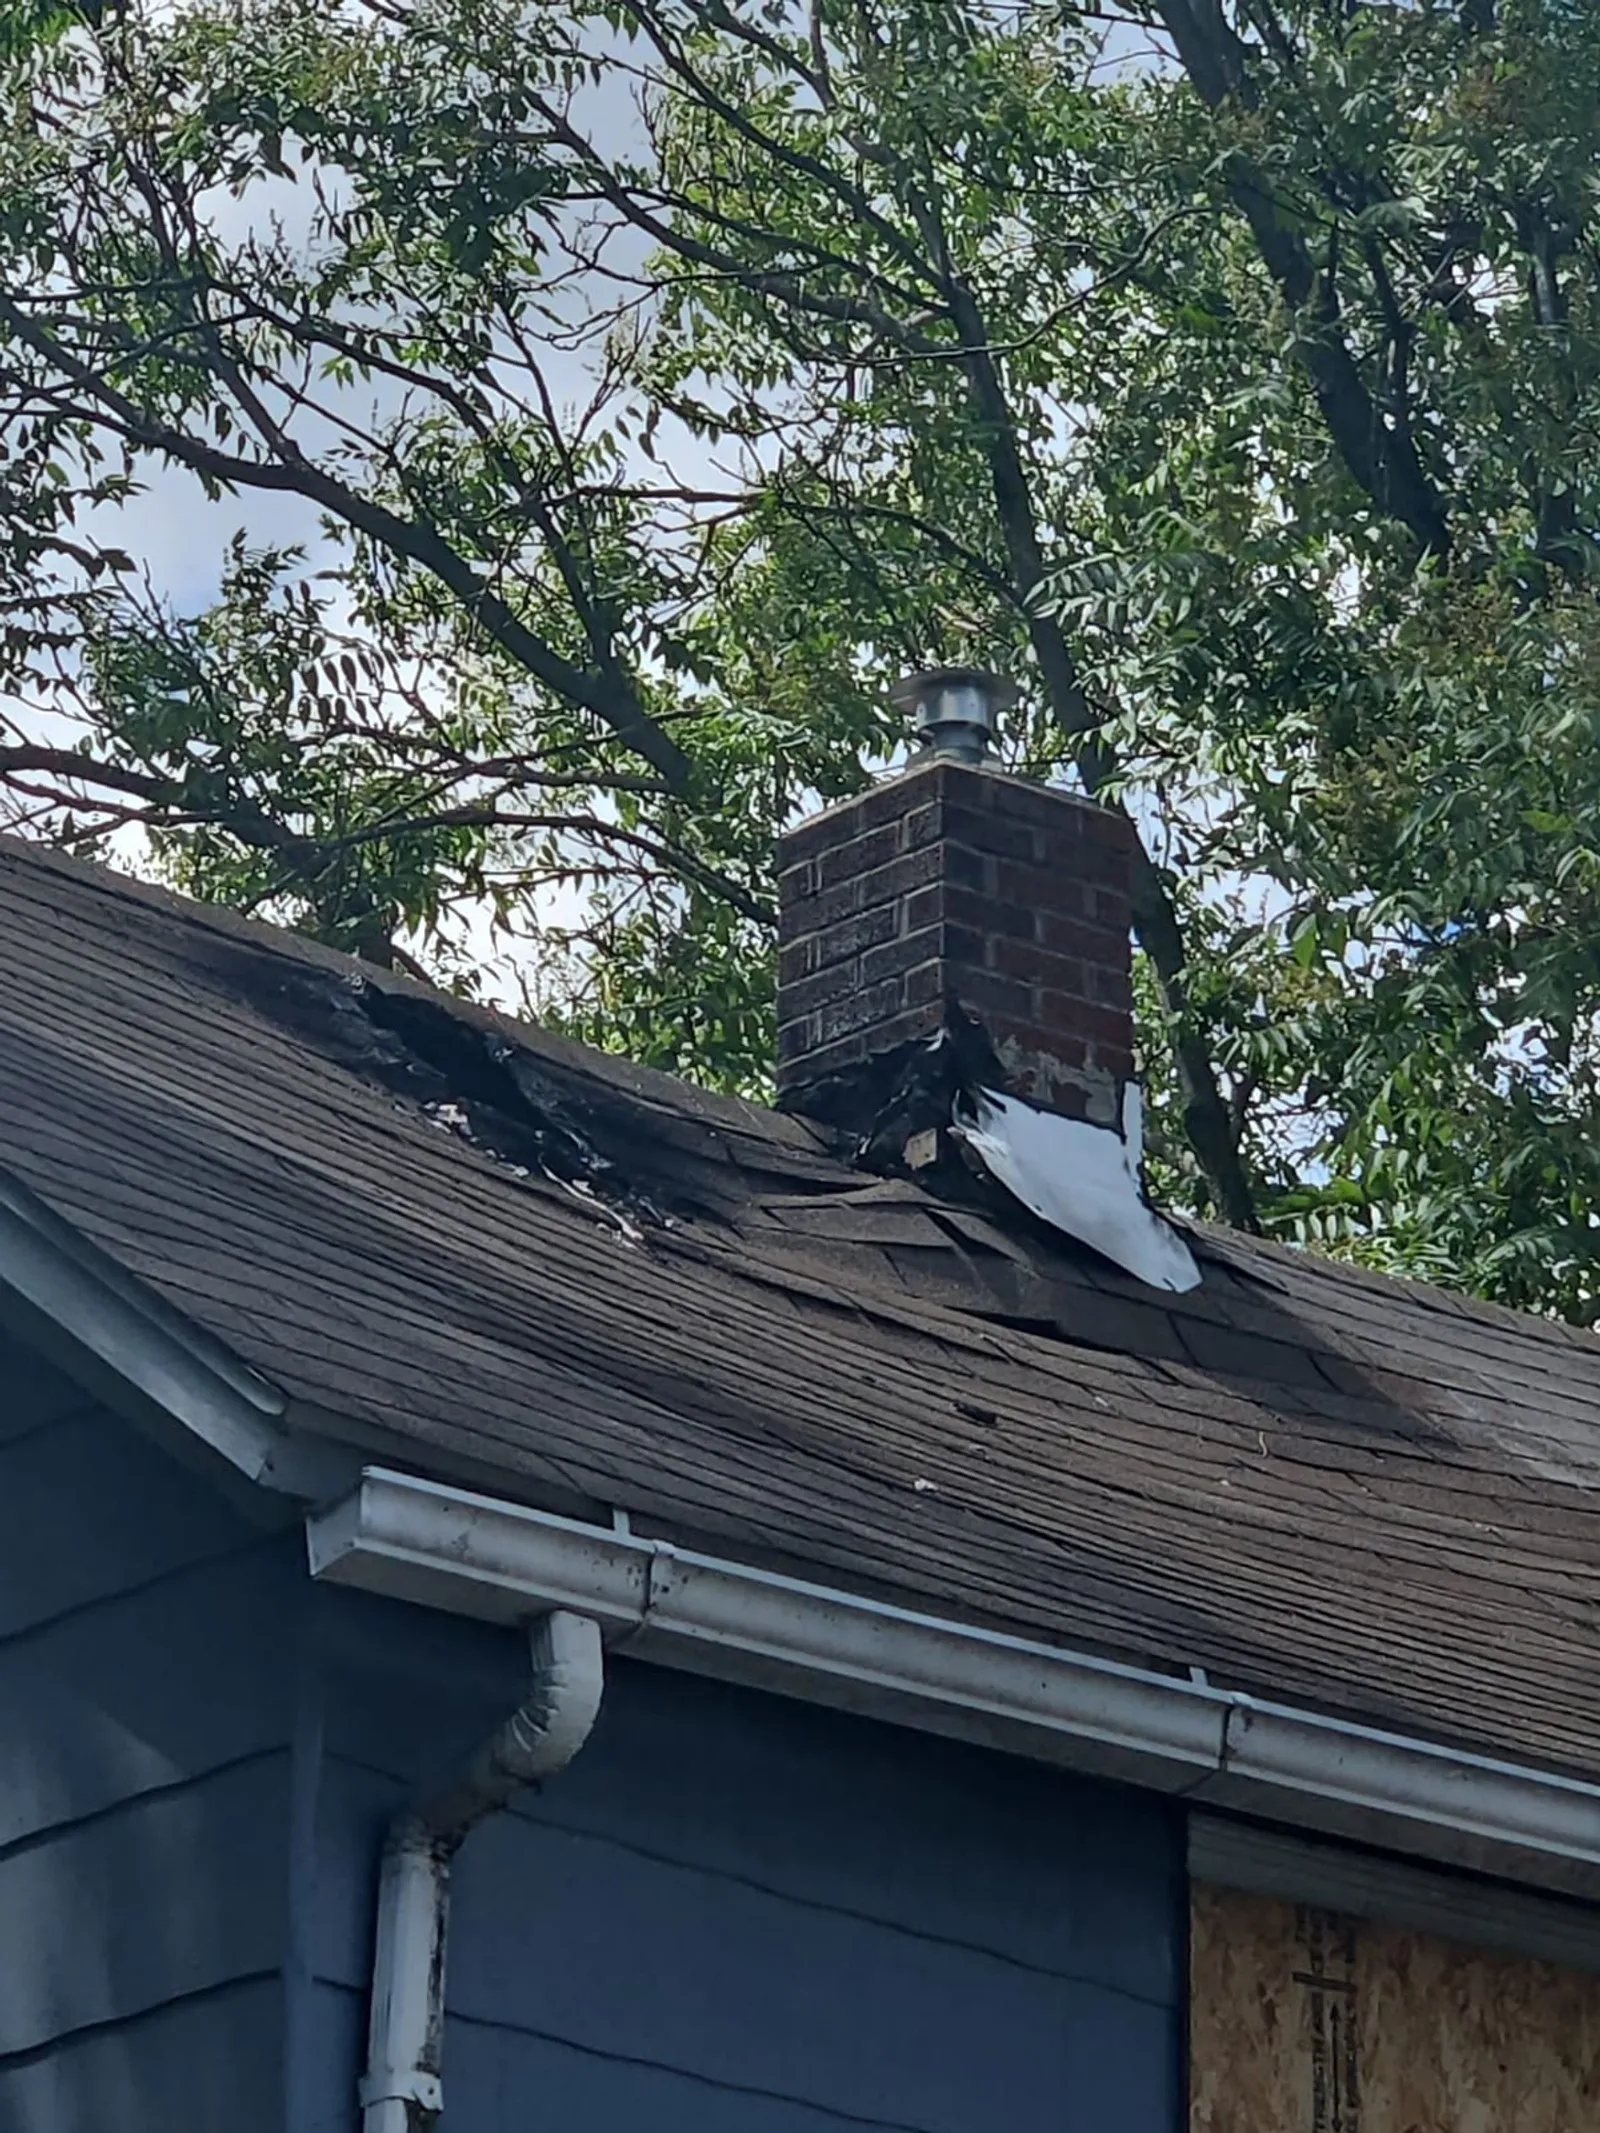
The most common problem isn't a denial — it's a lowball. The carrier's adjuster writes up the visible burn area and leaves out smoke and soot contamination, structural framing weakened by heat, water and mold from firefighting, ductwork, code upgrades, and contents. We re-inspect and supplement the claim for what was missed.
Your claim is stuck or delayed
Weeks of silence, repeated requests for the same documents, or an inspection that never gets scheduled. A delayed fire claim is money you're owed sitting unpaid. We push the file forward and keep the pressure on so it gets resolved.
How we reopen or supplement a fire claim
The same documentation that turns a lowball estimate into a fair settlement on a new claim also works to reopen one that's already been denied or underpaid.
Free claim review
We read your policy, the carrier's estimate, and the denial or offer letter — and tell you honestly whether the claim is being underpaid and what it's likely worth.
Re-inspect and document
We re-inspect the loss the way a builder does — using thermal imaging, moisture readings, and 3D scanning to capture the smoke, structural, and water damage the carrier's estimate left out.
Prepare the supplement
We build a full damage report and line-item estimate for the complete loss, then file it as a supplement or dispute to the existing claim.
Negotiate the settlement
We handle the back-and-forth with the insurer and negotiate for a fair, fully documented payout — so you don't have to fight it alone.
Why homeowners bring us in
- Licensed public adjusters serving Ohio and Florida (and more) — since 2006
- We work for you, not the insurance company
- Our fees are contingency-based and subject to applicable state law and the terms of your written agreement
- Thermal imaging, moisture detection, and 3D documentation of the full loss
- We handle the insurer negotiation start to finish
Insurance policies set deadlines for disputing or supplementing a claim, so it's worth having your fire claim reviewed sooner rather than later.
Denied & underpaid fire claims — common questions
Can a public adjuster reopen a denied fire claim?
Often, yes. A denial can frequently be challenged — over the stated cause of loss, a disputed exclusion, or incomplete documentation. A public adjuster reviews the denial and your policy, rebuilds the evidence, and disputes the basis for the denial. We'll tell you honestly whether we think there's a case before you commit to anything.
My fire claim was underpaid — is it too late to dispute it?
Usually you can still supplement or reopen an underpaid claim, even after the insurer's adjuster has already been out and made an offer, as long as it's within your policy's deadlines. That's why it's worth having someone review it sooner rather than later.
Can I hire a public adjuster after I already filed?
Yes. You can bring in a public adjuster at any stage — after you file, after the insurer's inspection, after an offer, or after a denial. We work for you, not the insurance company.
What does a public adjuster cost?
Our fees are contingency-based and subject to applicable state law and the terms of your written agreement. There's no cost for the initial claim review.
Do you handle fire claims in Ohio and Florida?
Yes — we're headquartered in Seven Hills, Ohio (Greater Cleveland) and licensed across multiple states including Ohio and Florida. We handle fire and smoke claim disputes in both.
Other Damage We Handle
Related Services
Denied or Underpaid? Get a Free Second Opinion.
We'll review your fire claim and the insurer's offer at no cost. Our fees are contingency-based and subject to applicable state law and the terms of your written agreement.